


Morning Brief
Headline News:
Equity futures point to a slightly lower opening this morning, as investors assess the recent rise in Treasury yields and continued pressure on semiconductor stocks. On the interest rate front, Fed Governor Christopher Waller said the increase in Treasury yields reflects stronger growth expectations rather than concerns about inflation, according to Reuters. Yields are easing this morning as trading resumes following yesterday’s Columbus Day bond market closure, with a decline in crude oil prices providing some relief. Overseas, European markets are mostly higher, supported by lower oil prices and bond yields.
Asian technology markets, however, faced renewed selling pressure amid concerns about elevated AI valuations, substantial capital spending commitments, and growing competition in memory chips. According to Bloomberg, China’s CXMT has claimed a breakthrough in memory technology that could put it ahead of established manufacturers Samsung and SK Hynix, adding to concerns about competition in the industry. Meanwhile, global semiconductor stocks are also facing pressure following Financial Times reporting that a large semiconductor company’s CEO compared aspects of the AI trade to gambling, adding to questions surrounding the sustainability of AI-related investment and valuations.
Meanwhile, Q3 earnings season is ramping up today, with several major banking and health care companies reporting results. The reports will provide an early look at corporate earnings trends as investors assess the outlook for the broader economy. The NFIB Small Business Optimism Index slipped in September and was just below consensus. Existing home sales are due at 10:00 a.m. ET, while several Dow components are in focus following their quarterly reports.
(Michael Gibbs, Managing Director, Lead Portfolio Manager )
Markets:
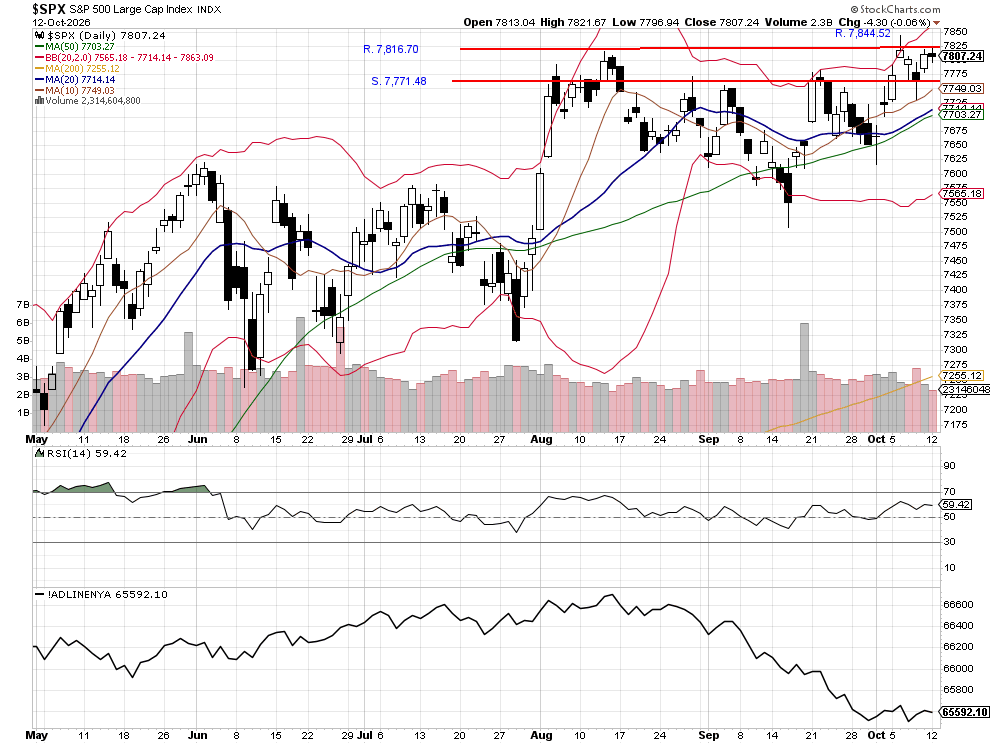
The S&P 500 rallied to test the resistance level at 7,816.70, where selling pressure emerged and pushed the index lower to close at 7,807.24. Despite the modest decline, the index traded within a relatively tight range, suggesting that sellers have not gained meaningful control of the market.
The narrow trading range is potentially constructive for the bullish trend, particularly if tomorrow morning’s September CPI inflation report comes in weaker than expected. A softer inflation reading could ease concerns about interest rates, encourage renewed buying, and provide the catalyst needed for the S&P 500 to break above resistance at 7,816.70.
However, a stronger-than-expected inflation report could trigger additional selling pressure and lead to a test of lower support levels.
Our outlook remains cautiously bullish, although we anticipate another session of muted, range-bound trading today as investors await tomorrow’s CPI report. A decisive breakout above 7,816.70, supported by improving market breadth and RSI momentum, would strengthen the case for a continuation of the uptrend.
Key Technical Outlook: The S&P 500 remains in a consolidation phase just below resistance. The ability to hold near current levels is encouraging, but a sustained breakout will likely require a favorable inflation report and broader buying participation.
John N. Lilly III CPFA
Accredited Portfolio Management Advisor℠
Accredited Asset Management Specialist℠
Portfolio Manager, RJFS
Partner, DJWMG
Windsor Wealth Planners & Strategists
Futures trading is speculative, leveraged, and involves substantial risks. Investing always involves risk, including the loss of principal, and futures trading could present additional risk due to underlying commodity investments.
The Relative Strength Index (RSI), developed by J. Welles Wilder, is a momentum oscillator that measures the speed and changes of price movements.
The percentage of stocks trading above a specific moving average is a breadth indicator that measures the underlying index’s internal strength or weakness. The 50-day moving average is used for short- to medium-term timeframes, while the 150-day and 200-day moving averages are used for medium- to long-term timeframes. Signals can be derived from overbought/oversold levels, crosses above/below 50%, and bullish/bearish divergences.
The Dow Jones Industrial Average (DJIA), commonly known as “The Dow,” is an index representing 30 stocks of companies maintained and reviewed by the editors of the Wall Street Journal. The Russell 2000 Index measures the performance of the 2,000 smallest companies in the Russell 3000 Index, which represents approximately 8% of the Russell 3000 Index’s total market capitalization.
The S&P 500 is an unmanaged index of 500 widely held stocks that is generally considered representative of the U.S. stock market. Past performance may not be indicative of future results. Keep in mind that individuals cannot invest directly in any index, and index performance does not include transaction costs or other fees, which will affect actual investment performance. Individual investors’ results will vary. Opinions expressed are those of the author, John N. Lilly III, and not necessarily those of Raymond James. “There is no guarantee that these statements, opinions, or forecast provided herein will prove to be correct. “The information contained was received from sources believed to be reliable, but accuracy is not guaranteed. Investing always involves risk, and you may incur a profit or loss. No investment strategy can guarantee success. The charts and/or tables presented herein are for illustrative purposes only and should not be considered as the sole basis for your investment decision. International investing involves special risks, including currency fluctuations, different financial accounting standards, and possible political and economic volatility. Investing in emerging markets can be riskier than investing in well-established foreign markets.
This is not a recommendation to buy or sell any company’s stock mentioned above.
US government bonds and treasury bills are guaranteed by the US government and, if held to maturity, offer a fixed rate of return and guaranteed principal value. US government bonds are issued and guaranteed by the federal government’s timely payment of principal and interest. Bond prices and yields are subject to change based on market conditions and availability. If bonds are sold prior to maturity, you may receive more or less than your initial investment. Holding bonds to term allows redemption at par value. There is an inverse relationship between interest rate movements and bond prices. Generally, when interest rates rise, bond prices fall, and when interest rates fall, bond prices generally rise.
The Nasdaq 100 (^NDX) is a stock market index comprising 103 equity securities of 100 of the largest non-financial companies listed on the NASDAQ. It is a modified capitalization-weighted index. It is based on exchange and not an index of U.S.-based companies.
The Russell 2000 Index is a stock market index that measures the performance of the 2,000 smaller companies included in the Russell 3000 Index. It is managed by London’s FTSE Russell Group and is widely regarded as a bellwether of the U.S. economy because it tracks smaller companies that operate in the U.S. market.
The NYSE advance/decline measure refers to the number of common stocks listed on the New York Stock Exchange (NYSE) that close at a higher price than their previous closing price (“advancing issues”) compared to the number of NYSE-listed common stocks that close at a lower price than their previous closing price (“declining issues”) during a specified trading session.
This measure serves as an indicator of market breadth and reflects the extent to which price movements are broadly distributed across NYSE-listed securities.